Common Contingencies in a Greater Baton Rouge Purchase Agreement: What Buyers and Sellers Need to Know in 2026
Real estate contingencies are contractual safeguards built into Louisiana purchase agreements that protect both buyers and sellers by defining the conditions under which a deal can proceed, be renegotiated, or be cancelled. The Louisiana Real Estate Commission mandated a revised Residential Agreement to Buy or Sell effective January 1, 2026, introducing new requirements for cash buyer proof of funds and buyer broker compensation disclosures. Understanding how these clauses work—and when they apply—can help Greater Baton Rouge buyers protect their earnest money and help sellers evaluate the true strength of any offer they receive.
What Are Real Estate Contingencies and Why Do They Matter in Greater Baton Rouge?
In Greater Baton Rouge, contingencies are standard components of nearly every residential transaction. They are not loopholes or signs of a weak offer—they are the structured framework that defines each party's rights and obligations from the moment a contract is signed to the day of closing. The governing document in Louisiana is the Residential Agreement to Buy or Sell, which the Louisiana Real Estate Commission (LREC) oversees and periodically revises. Effective January 1, 2026, the LREC mandated updates to this form, reinforcing the importance of understanding not just what contingencies exist, but how the specific language of the current agreement shapes them.
For buyers, contingencies are primarily a financial safety net. They define the circumstances under which earnest money—the good-faith deposit submitted with an offer—can be returned if the deal falls apart for a covered reason. For sellers, contingencies establish clear timelines and conditions, giving them a structured path toward closing and, in some cases, the ability to continue marketing the property if a buyer's conditions are not satisfied. In a market where contingent listings are common, both sides benefit from knowing exactly what each clause requires and what happens when a deadline passes.
The Five Most Common Contingencies—and How Each One Protects You
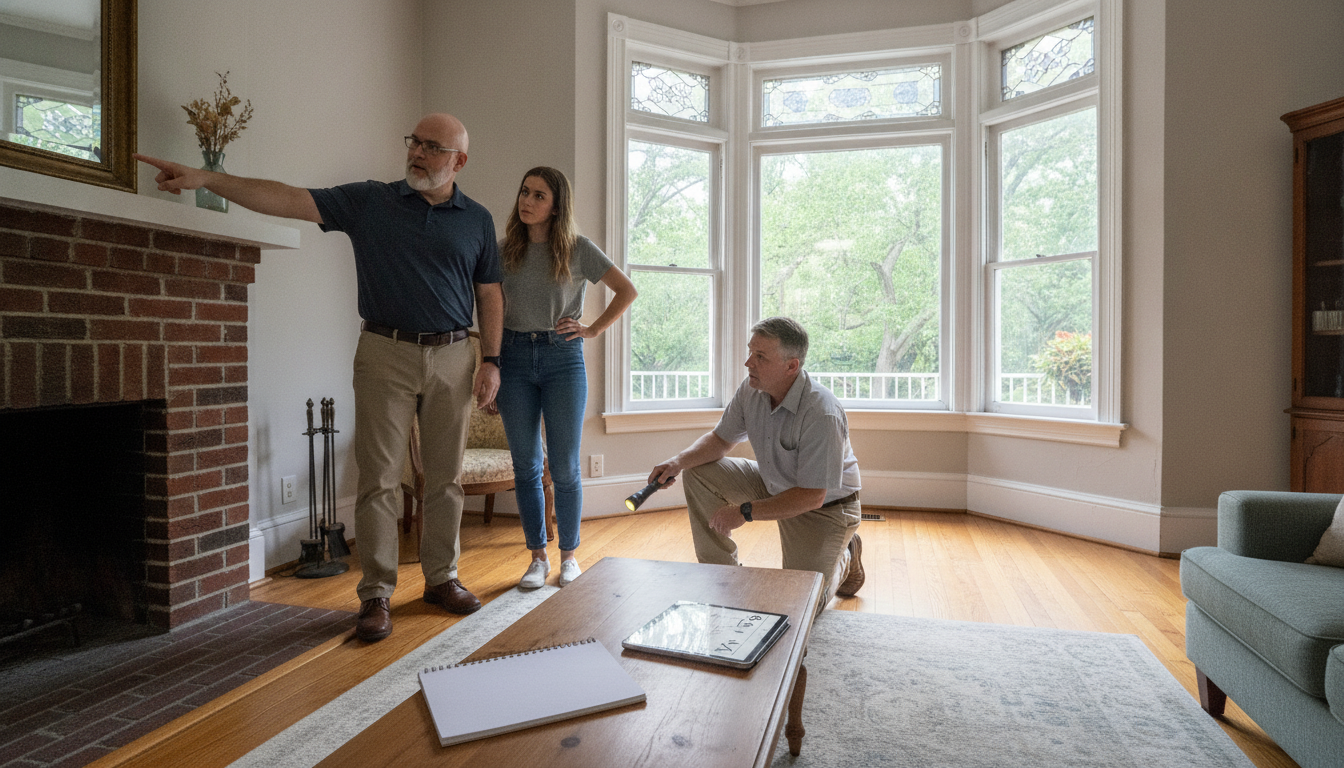
**Inspection Contingency:** Typically grants the buyer a set period—often cited in Louisiana practice as roughly 10 to 14 days, though the specific number of days is negotiated and written into the contract—to have the property professionally inspected. If serious issues are discovered, the buyer may request repairs, negotiate a price reduction, or exit the contract and recover their earnest money. Sellers benefit from a structured process: once the buyer accepts the property's condition or the deadline passes without action, the contingency is removed and the transaction moves forward. Waiving this contingency, particularly for older homes, carries meaningful financial exposure for buyers.
**Financing Contingency:** Protects buyers who are using a mortgage by specifying loan type, terms, and a deadline to secure approval. If the buyer cannot obtain financing for a covered reason within the agreed period, they can exit without forfeiting their deposit. For sellers, it sets a firm deadline that confirms the buyer's financial capability.
**Appraisal Contingency:** If the lender's appraiser values the property below the purchase price, the buyer may renegotiate, bring additional cash to closing, or terminate the contract and recover their deposit. Lenders generally require an appraisal before funding a loan, making this contingency closely linked to the financing contingency in practice.
**Home Sale Contingency:** Makes the purchase conditional on the buyer's existing home selling first. Many of these include a kick-out clause—sometimes called a 72-hour clause—allowing the seller to continue marketing and accept a competing offer, giving the original buyer a short window to remove the contingency or walk away.
**Title Contingency:** Conditions the sale on the seller delivering a clear, merchantable title free of undisclosed liens, encumbrances, or ownership disputes. Under the Louisiana Residential Agreement to Buy or Sell, all costs and fees required to make title merchantable are the seller's responsibility. If title issues cannot be resolved, the buyer can demand return of their deposit. Sellers bear the obligation to clear title before closing.
2026 LREC Form Updates: What's New and Why It Matters at the Contract Table
The 2026 updates to the Louisiana Residential Agreement to Buy or Sell do not add new contingencies in the traditional sense, but they do strengthen the protective framework around two areas that had previously been handled less formally.
**Cash Buyer Proof of Funds:** The revised form explicitly requires cash buyers to provide documentation of their financial capability—such as a bank statement or letter of financial capability—within a specified number of days stated in the contract. If that documentation is not delivered on time, the seller has an explicit contractual right to terminate the agreement. The new language also grants the seller and their agent permission to contact the financial institution to verify the authenticity of the documentation provided. This change directly addresses a practical risk sellers face when accepting cash offers: the possibility that a buyer's claimed funds do not actually exist or are not accessible. Sellers evaluating cash offers in 2026 should confirm that the proof-of-funds deadline and verification language are properly included in the agreement.
**Buyer Broker Compensation Disclosure:** The 2026 agreement includes a dedicated section—new as of this form version—disclosing the amount the seller agrees to contribute toward the buyer's broker compensation at closing, with clarification that this amount is disbursed from the seller's proceeds. This change increases transparency for all parties and reflects broader industry shifts in how buyer agent compensation is documented in purchase agreements.
Buyers and sellers should review the current LREC-mandated form with their agent and, where appropriate, with a licensed Louisiana real estate attorney, to understand how these provisions apply to their specific transaction.
Practical Decision Points: Questions to Ask, Documents to Gather, and Professionals to Involve
**For Buyers — Key Decision Points:**
– *Know your deadlines.* Every contingency has a contractual timeframe. Missing a deadline—even by a day—can cost you your right to exit without penalty. Your agent should track these dates and prompt you well in advance.
– *Understand what you're waiving.* In competitive situations, buyers sometimes consider waiving inspection or appraisal contingencies to strengthen an offer. This is a significant financial decision. Discuss the specific risks with your agent before agreeing to waive any protection, particularly for older properties where undisclosed issues are more likely.
– *Protect your earnest money.* If you exit a contract under a valid, properly documented contingency within the allowed window, you are generally entitled to a full return of your deposit. Exiting outside a contingency window or for a reason not covered by the contract may result in forfeiture.
– *Cash buyers: prepare your documentation.* The 2026 LREC form requires proof of funds within a specified number of days. Have your bank statement or financial capability letter ready before you make an offer.
**For Sellers — Key Decision Points:**
– *Evaluate offer strength beyond price.* A higher offer with multiple contingencies may carry more risk than a slightly lower offer with fewer conditions. Your agent can help you compare offers on a risk-adjusted basis.
– *Insist on kick-out clauses.* If you accept a home sale contingency, ensure the agreement includes a kick-out clause so you retain the right to continue marketing and respond to competing offers.
– *Verify cash offer documentation.* Under the 2026 form, you have the right to request and verify proof of funds. Use it.
**Professionals to Involve:** A licensed Louisiana real estate attorney can review contract language, advise on your rights under specific contingency clauses, and assist if a dispute arises. Your lender should be engaged early to confirm financing timelines align with contract deadlines. A licensed home inspector should be scheduled promptly once a contract is signed so the inspection contingency window is not wasted.
Baton Rouge Home Seller FAQ
What happens to my earnest money if a contingency is not met in Louisiana?
If a buyer exits a Louisiana purchase agreement under a valid, properly documented contingency within the contractually specified timeframe, they are generally entitled to a full return of their earnest money deposit. However, if a buyer attempts to cancel outside a contingency window or for a reason not covered by the contract, the seller may have grounds to retain the deposit. The specific terms governing earnest money are defined in the Residential Agreement to Buy or Sell, so reviewing that language carefully with your agent—and a real estate attorney if needed—is important before signing.
What is a kick-out clause, and should sellers in Greater Baton Rouge require one?
A kick-out clause (sometimes called a 72-hour clause or bump clause) allows a seller who has accepted a home sale contingency to continue marketing the property and accept a competing non-contingent offer. When a new offer comes in, the original buyer typically has a short window—often ranging from 24 to 72 hours, as negotiated in the contract—to either remove their home sale contingency and proceed or walk away. For sellers in move-up buyer communities like Prairieville, Gonzales, and Denham Springs, where home sale contingencies are common, including a kick-out clause is a practical way to limit the risk of having a property tied up indefinitely.
What are the new cash buyer proof-of-funds requirements under the 2026 Louisiana purchase agreement?
Effective January 1, 2026, the LREC-mandated Residential Agreement to Buy or Sell explicitly requires cash buyers to provide documentation of their financial capability—such as a bank statement or letter of financial capability—within a number of days specified in the contract. If the documentation is not provided on time, the seller has an explicit right to terminate the agreement. The revised form also grants the seller and their agent permission to contact the financial institution to verify the authenticity of the documentation. Cash buyers should have these materials ready before submitting an offer.
Should a buyer ever consider waiving a contingency in Greater Baton Rouge?
In competitive market conditions, some buyers consider waiving inspection or appraisal contingencies to make their offer more attractive to sellers. However, waiving these protections carries real financial risk: without an inspection contingency, a buyer who discovers serious defects after closing has limited recourse; without an appraisal contingency, a buyer may be obligated to cover the gap between the appraised value and the purchase price out of pocket. This decision deserves a thorough conversation with your agent about the specific property, its age, condition, and the current competitive environment—particularly for older homes in neighborhoods like the Garden District or Mid-City Baton Rouge.
How does the appraisal contingency interact with the financing contingency in a Louisiana purchase agreement?
These two contingencies are closely related in practice. Lenders generally require an appraisal before funding a mortgage to confirm the property is worth the amount being borrowed. If the appraisal comes in below the purchase price, it can trigger both contingencies: the financing contingency may be affected if the lender will not fund the full loan amount, and the appraisal contingency gives the buyer the option to renegotiate the price, bring additional cash to closing to cover the gap, or exit the contract and recover their deposit. Buyers relying on mortgage financing should understand how both clauses work together before signing.
Sources
- LREC 2026 Mandatory Forms Announcement
- Louisiana REALTORS® — 2026 Changes to Purchase Agreement and Property Disclosure
- Service 1st Real Estate — 2026 Purchase Agreement Overhaul Guide
- MovingTo225 — What Does Contingent Mean in Real Estate: A Baton Rouge Buyer's Guide
- Crescent City Living — Louisiana Real Estate Contract Overview
- Champagne Living — How to Spot a Real Cash Buyer in Louisiana: New 2026 Rules
- Rocket Mortgage — Kick-Out Clause Explained